March’s data continues to reinforce a clear and consistent theme: Ottawa’s housing market is recalibrating rather than shifting into contraction.
Activity levels have softened compared to last year, but the underlying structure of the market remains intact. Properties are still trading across all major segments, and there is no evidence of systemic stress. What has changed is behaviour—buyers are more deliberate, more selective, and more sensitive to pricing than they were during the highly constrained conditions of 2020–2022.
In practical terms, this is not a withdrawal of demand. It is a normalization of decision-making in a higher-rate, higher-choice environment. Sellers are no longer operating in a scarcity-driven market, and buyers are no longer forced into accelerated timelines. The result is a more balanced, but more segmented, landscape.
Headline Numbers
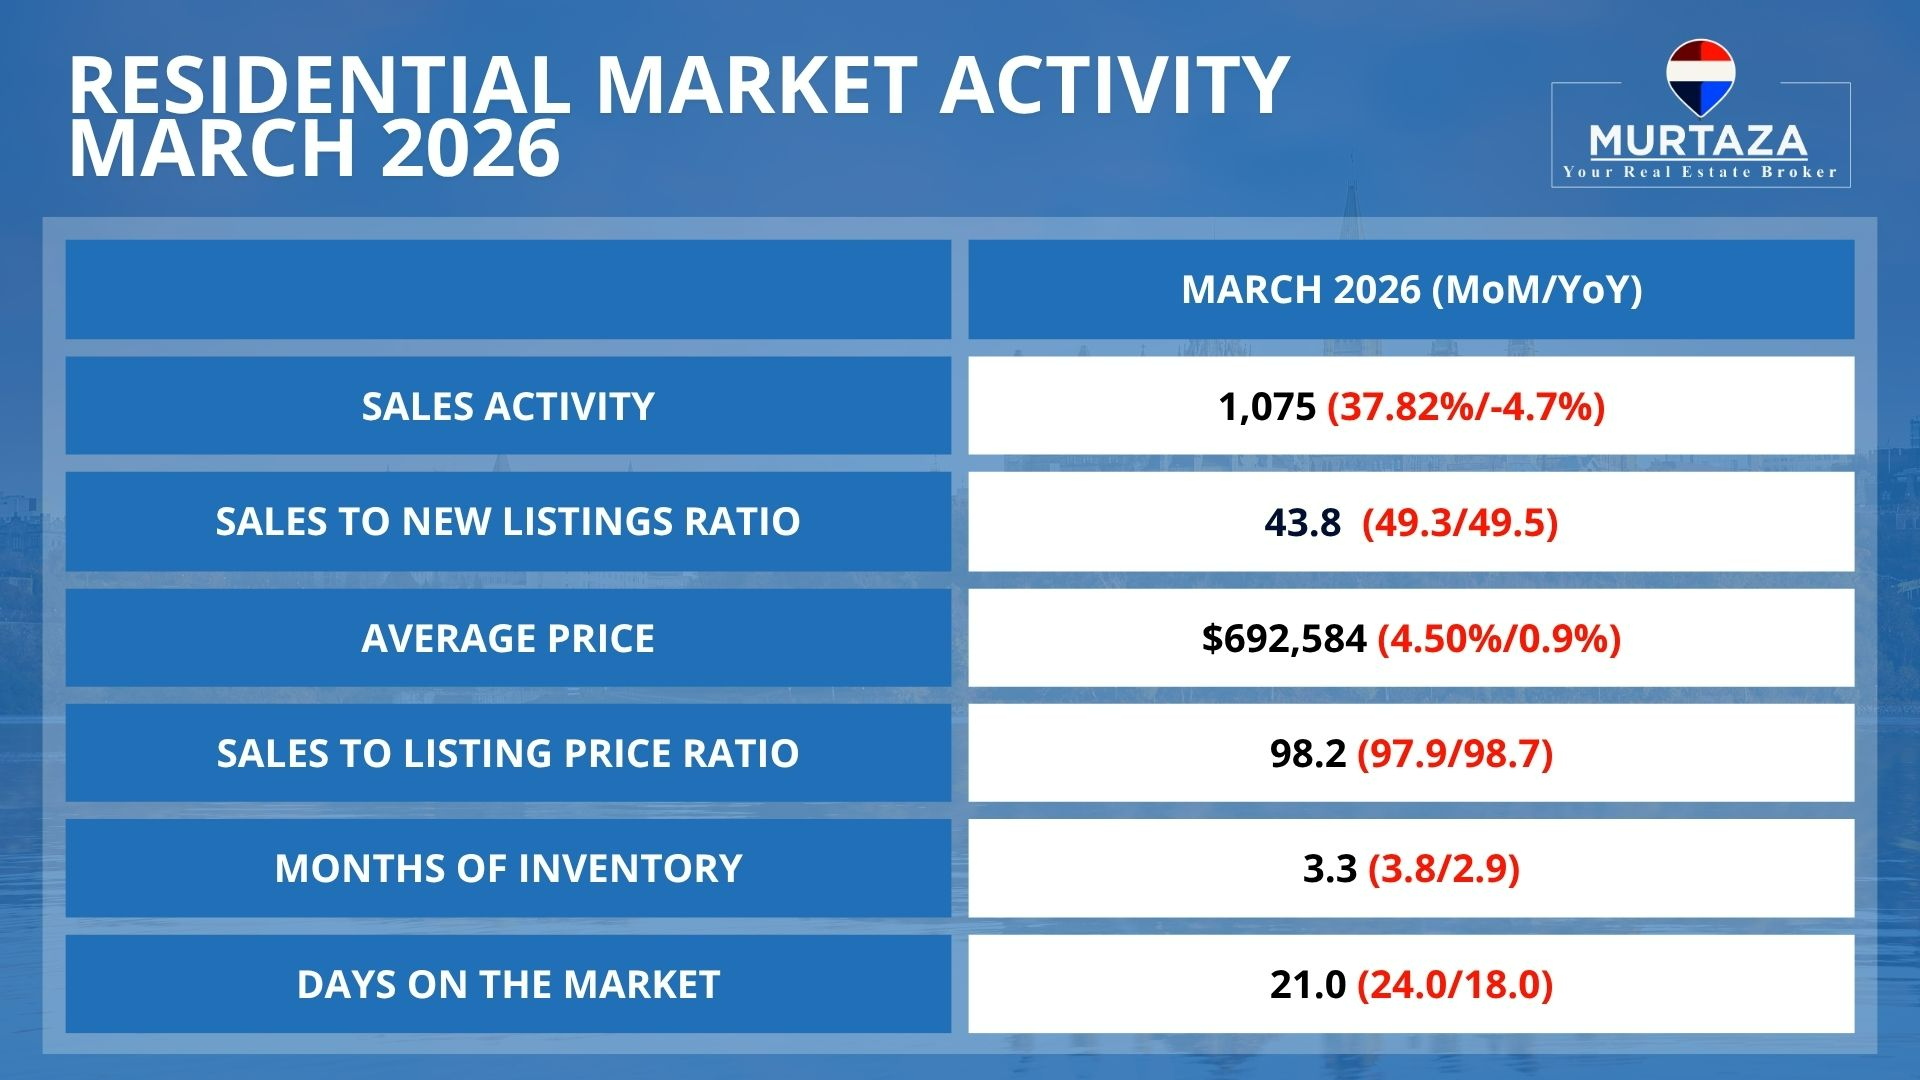
- Sales: 1,075 transactions (-4.7% YoY)
- Year-to-date sales: -5.7% YoY
- New listings: +7.5% YoY
- Active listings: +10.3% YoY
- Total inventory: 3,578 units
- Months of inventory (MOI): 3.3 (vs. 2.9 last year)
- MLS® HPI Benchmark: -2.1% YoY
Interpretation:
The market is operating in balanced territory overall, but the balance is increasingly defined by segmentation rather than uniform conditions. Supply has expanded at a faster pace than demand, but not to levels that indicate oversupply. Price adjustments remain gradual and selective rather than broad-based.
Demand Conditions
Buyer activity in March remained steady, though clearly more measured than in previous cycles.
Demand is being shaped by three primary factors:
- Rate sensitivity: Borrowing costs remain elevated relative to long-term norms, limiting affordability at the margin.
- Increased choice: Higher inventory levels are reducing urgency and extending decision timelines.
- Selective engagement: Buyers are active, but only committing when pricing aligns closely with perceived value.
Demand has not collapsed—it has normalized. There is still consistent absorption across the market, particularly in well-priced properties. However, the pace of transactions reflects a more analytical buyer pool that is weighing options more carefully before committing.
Supply Conditions
On the supply side, conditions continue to shift toward greater balance.
- New listings are up 7.5% YoY
- Active listings are up 10.3% YoY
- Inventory now sits at 3,578 units
- MOI has increased to 3.3 months
This expansion in supply is the primary structural driver of current market behaviour.
Implications include:
- More visible competition between comparable listings
- Increased importance of pricing precision at launch
- Longer exposure times for misaligned listings
- Greater leverage shifting toward buyers in mid- and upper-price segments
However, this is not an oversupplied market. Instead, it is a market where supply has recovered from constrained levels and is now interacting more efficiently with demand.
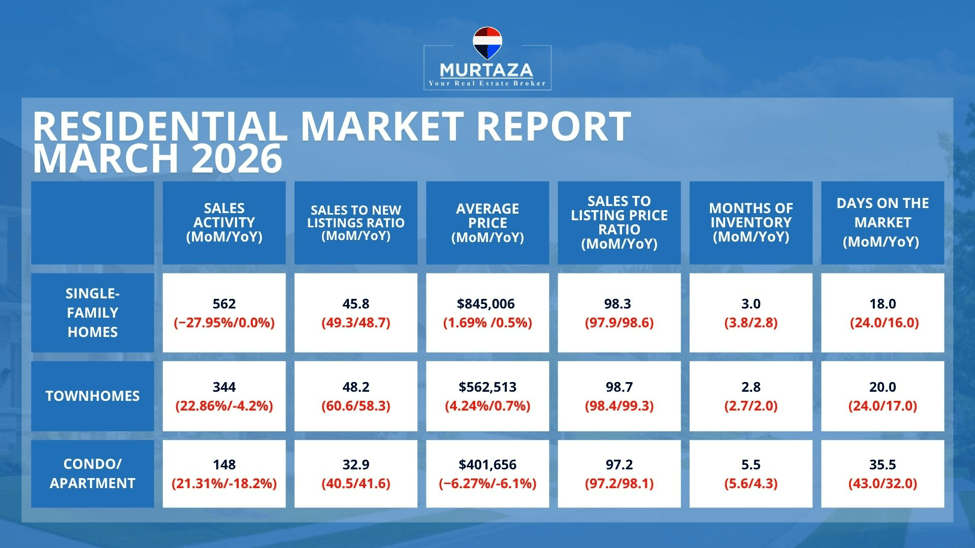
Segment Analysis
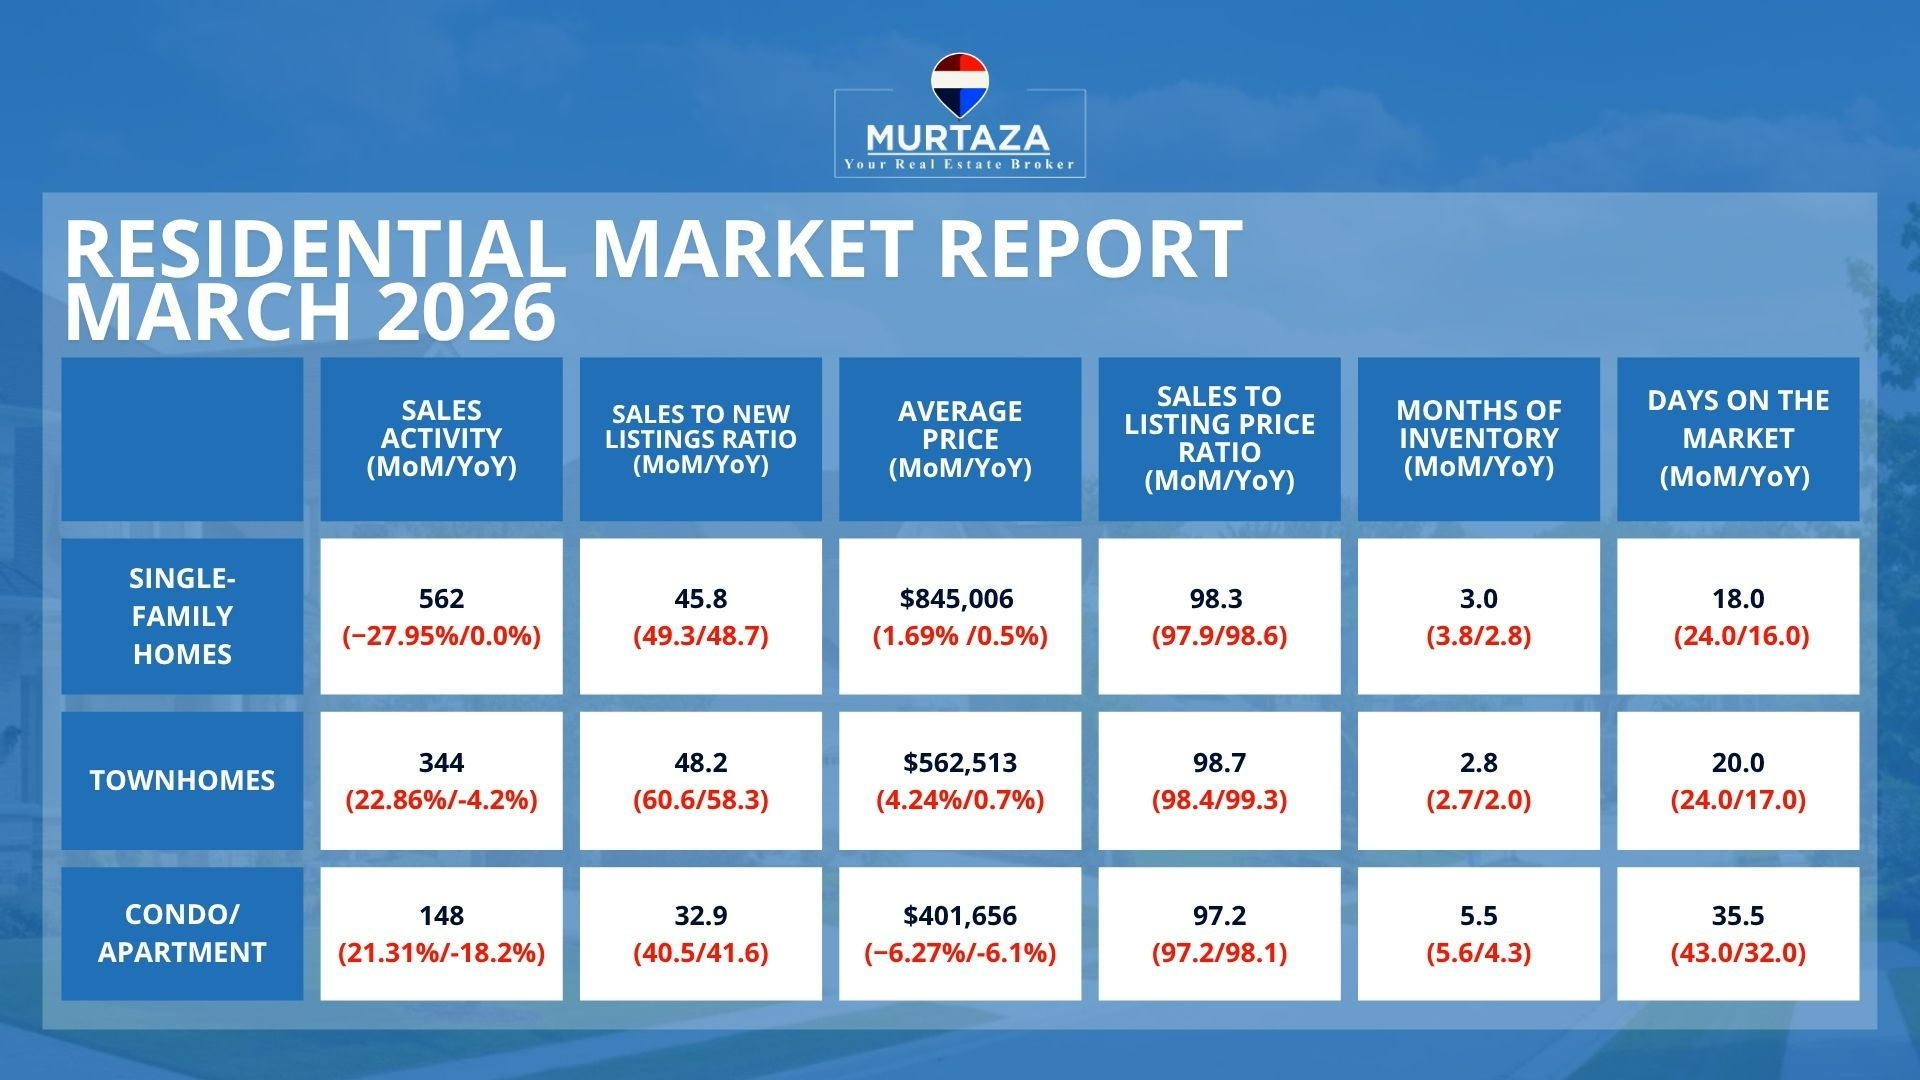
Detached Homes (Anchor Segment)
Detached homes remain the most stable segment of the market.
- MOI: ~3 months
- Pricing: broadly stable
- Demand: consistent, equity-driven participation
Detached properties continue to attract end-user and move-up buyers, particularly those with accumulated equity. While negotiation has increased, well-positioned homes are still transacting within reasonable timeframes.
Interpretation:
Balanced-to-slightly-competitive conditions. Execution and pricing strategy remain the key differentiators.
Townhomes (Affordability-Sensitive Segment)
Townhomes are experiencing more visible adjustment.
- Inventory: increasing
- Pricing: modest softening
- Demand: steady but more price-sensitive
This segment is highly responsive to affordability constraints. Buyers remain active, but are increasingly disciplined in comparing alternatives.
Interpretation:
Performance is highly dependent on pricing accuracy. Proper positioning drives absorption; mispricing leads to stagnation.
Apartments / Condos (Pressure Segment)
The condo segment remains the most challenged area of the market.
- Sales: -18.2% YoY
- MOI: 5.5 months
- Pricing: declining
Investor participation has slowed, and carrying cost sensitivity continues to weigh on demand.
Interpretation:
A structurally adjusted segment. Conditions are likely to remain softer relative to other housing types until affordability and rate dynamics shift meaningfully.
Pricing Trends
The MLS® HPI benchmark shows a -2.1% YoY decline, reflecting gradual and controlled repricing.
This is not a sharp correction, but a slow alignment between pricing expectations and current market realities.
Key characteristics:
- Stability in well-priced, ground-oriented homes
- Selective downward adjustment in overlisted or investor-heavy segments
- Strong correlation between pricing accuracy and sale velocity
Sale-to-list ratios remain firm where pricing is aligned with market conditions, reinforcing that this is a selective pricing market rather than a broadly discounted one.
Strategic Implications
This is not a market that rewards broad assumptions. It rewards precision.
For sellers:
Pricing strategy at launch remains the most important variable. The market is responsive, but not forgiving of misalignment.
For buyers:
Opportunity exists in increased inventory and segment-specific softness, particularly where pricing has drifted above current demand thresholds.
For professionals:
The advantage lies in interpreting absorption by segment and price band, not just reading headline averages.
Ottawa’s market continues to operate in a balanced, higher-rate environment where behaviour is normalizing and outcomes are increasingly segmented.
Demand remains present. Supply has rebuilt. Prices are adjusting gradually rather than abruptly. Importantly, there is no indication of distress-driven dynamics—only a more measured and selective marketplace.
This is a recalibrating market, not a retreating one.
If you’re considering buying, selling, or simply want a clearer understanding of where your property sits within today’s segmented market conditions, I’m always happy to provide a data-driven breakdown tailored to your situation.
Feel free to reply directly to this email or reach out to schedule a brief market consultation. Even a short conversation can help clarify timing, positioning, and strategy in a market like this.
Murtaza Siddiqui
Broker | RE/MAX Hallmark Realty Group
📧 [email protected]
📞 (613) 805-1111

